Industry insights
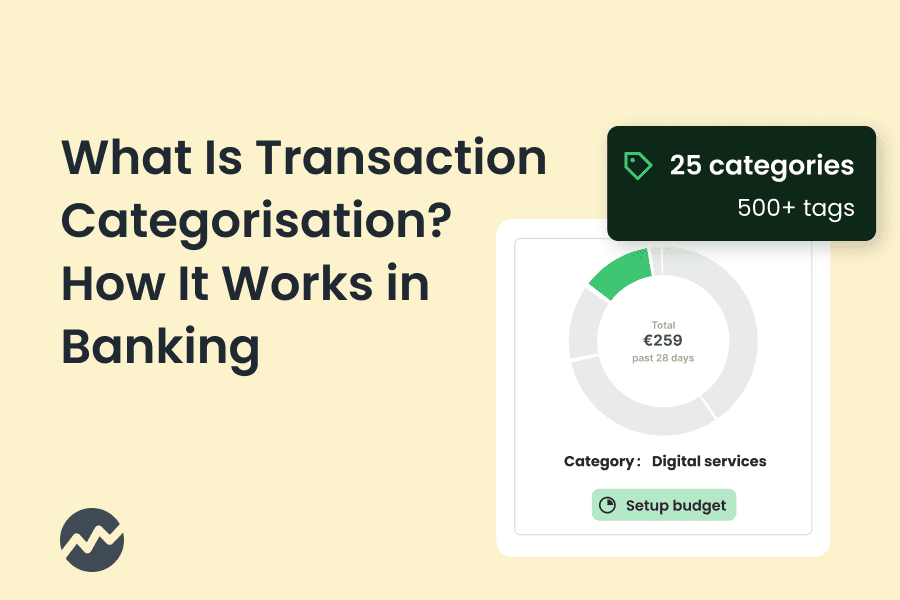
What is transaction categorisation and how does it work?
Every payment reaches a banking app as a few technical fields, such as a shortened merchant description, a four-digit code and a terminal number. Transaction categorisation turns them into a feed customers can read and budgets they can trust. Learn how it works, why MCC codes alone get only 63% of transactions right, and what banks can build on top of accurate categories.

Industry insights
Becoming the Bank of Choice: How to Stand Out From the Crowd
Switching banks is more common than one might think. According to a satisfaction survey conducted by J.D. Power, nearly 13% of consumers are expected to switch their primary bank this year. The most common reasons for this shift include high fees, poor customer service, lack of convenient digital banking features, and better offers from competitors. Is there a way to be a part of the client's life journey indefinitely? Let's find out.
Industry insights
Bending data: Essential building blocks for a perfect PFM platform
With banking going digital and more personal than ever before, Personal Financial Management tools (PFM for short) have become indispensable for individuals seeking to take control of their finances. To build the perfect one...

Industry insights
Youth Banking Trends: Mapping Digital Banks for Kids, Teens, and Gen Z
While digital banking is undergoing rapid transformation and growth, a new phenomenon is emerging – Kids Banking. This concept not only represents a unique way for today's children to learn about money but also offers a unique opportunity to develop financial literacy from a very young age. Fintechs such as Pocket, GoHenry and neobanks such as Revolut are jumping on the trend.

Industry insights
Subscription banking: Transaction data tells you what customers will pay for
Subscription banking is now a serious revenue line, with Revolut earning £708m from paid plans in 2025. But a paid tier only works when it is built around what customers already pay for, not around the bank’s existing portfolio. Drawing on a recent 11:FS Fintech Insider episode with bunq and Tapix, we look at how transaction data shows banks which tiers customers will actually keep paying for.
Industry insights
Top 135+ Fintech Conferences of 2027: Must-Attend Events for Industry Insights
Fintech and digital banking event lists exist, but they are often fragmented, incomplete, or hard to compare. Relevant conferences are spread across multiple sources with little structure. This curated overview brings them together in one place for 2027.

Industry insights
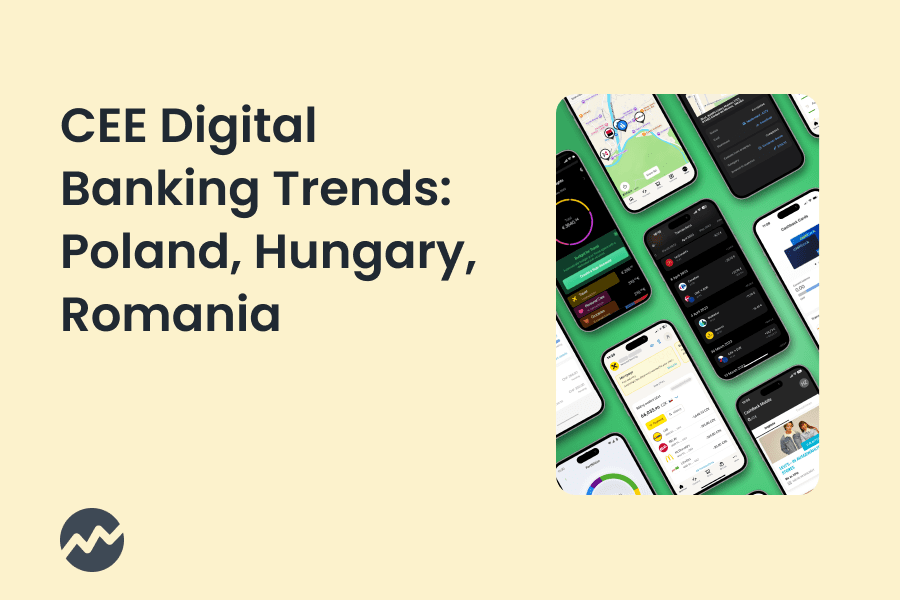
CEE Digital Banking Trends: What Poland, Hungary and Romania Reveal About the Next Five Years
Poland is CEE's most digitally mature market, yet Revolut's penetration there is barely half what it is in Hungary or Romania. Our benchmark of all three markets explains why, and identifies four trends that will decide who owns the customer relationship over the next five years.
Industry insights
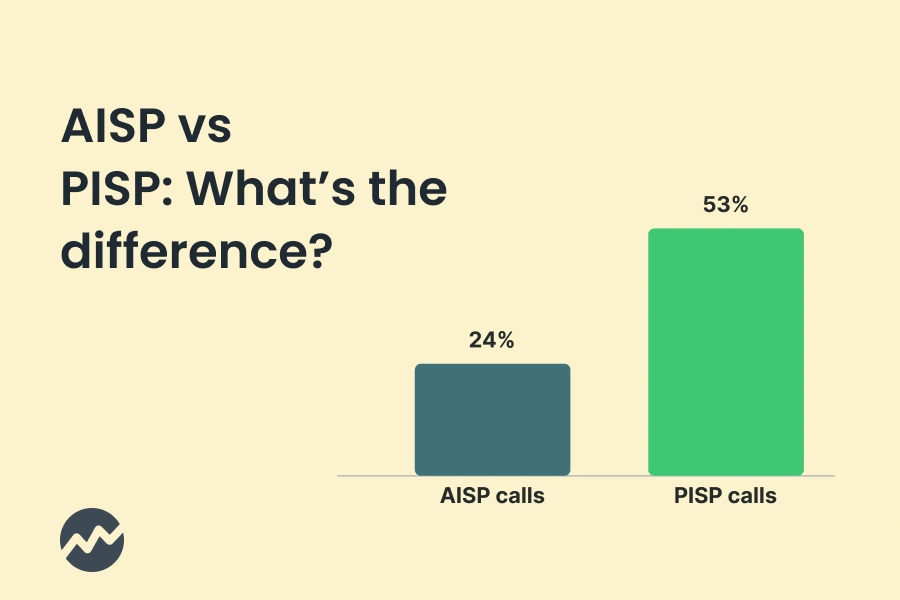
AISP vs PISP: reading payment data vs acting on it
Affordability comes down to one number a lender must evidence: what's left after every expense is paid. That's an account information job start to finish - and it's where the two open banking roles split. An AISP reads the transaction picture that makes affordability calculable; a PISP moves the money once the decision is made, but plays no part in working out whether someone can afford anything. Here's why the two belong in separate boxes, and why adoption is now tilting from the reading role toward the acting one.
Industry insights
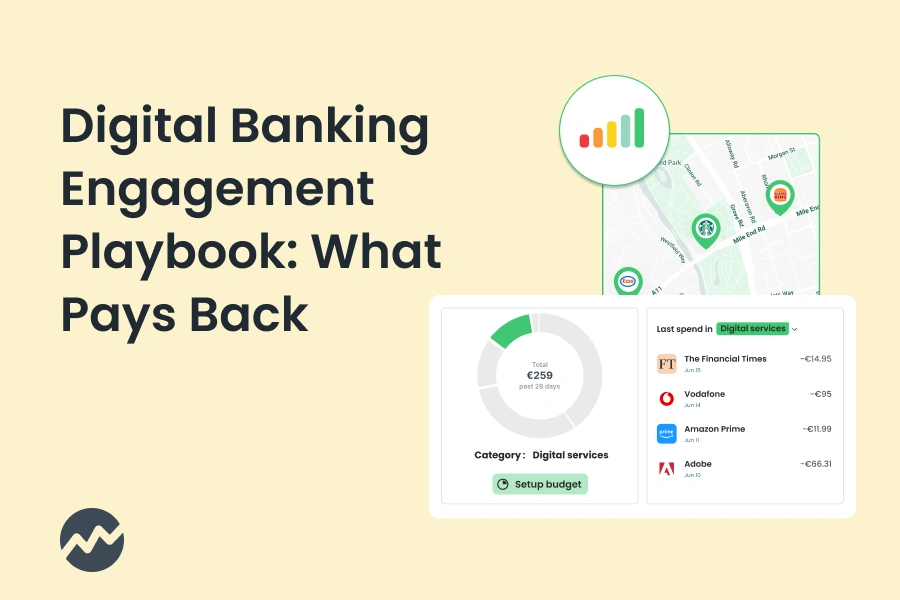
The Digital Banking Engagement Playbook: What Actually Pays Back
An established bank earns several times more per customer than a neobank, and almost none of it comes from the app. The money sits on the balance sheet: the salary paid in, the direct debits cleared against it, the loan on the other side of the ledger. But the app is where that relationship gets defended or quietly lost, feature by feature, as customers decide where their financial routine will live. This playbook cuts through engagement vanity metrics to the features that actually move the number that pays back - and shows why every one of them depends on a bank being able to read what its customers' payments really are.
Industry insights
AI Assistants in Banking: bunq, Starling and Revolut
Three banks shipped consumer-facing AI assistants inside twelve months, and to anyone being asked whether their own bank needs one, they look like a single trend. They are not. Measured on what the assistant is allowed to do, what it is allowed to see, and the route each bank took to ship it, bunq Finn, Starling Assistant and Revolut AIR turn out to be three different products - and the differences change what can go wrong with each. Here they are set side by side.
Industry insights
How enrichment expands personal finance management
Every feature in a personal finance app - categories, spending summaries, subscription alerts, carbon insights, even an agent that cancels a forgotten trial - sits on one thing: the quality of the transaction data underneath. Here's how enrichment turns raw payment strings into a PFM customers actually trust, across every payment rail and every market.

Industry insights
What does Generation Z expect from banking?
Gen Z is the heaviest-subscribing generation and fails on those subscriptions at roughly twice the rate of everyone else. But subscriptions are only the start. This piece breaks down four things Gen Z actually expects from a bank - seeing what they pay for, getting answers without digging, having their spending reflected back accurately, and banking with an institution that looks like them - and shows the European evidence behind each. Underneath all four sits the same dependency: a clean, enriched transaction record.

Industry insights
What Are MCC Codes, and Why Aren't They Enough for Transaction Categorisation?
We decided to provide our insights into the power of strictly MCC-based categorisation and its limits. Categorisation is important for credit risk scoring and it is the basis for Personal Finance Management tools. When we analysed our categorisation with MCCs, we saw that only 53% of transactions could be easily and reliably categorised based on their MCC code. Let's look at the most frequent problems we identified that make MCC usage more difficult than it may seem at first glance.


Industry insights
Top 5 Digital Banking Features for Generation Z
Gen Z decides fast whether a banking app is worth keeping open, and the choice comes down to five features: clear transaction history, subscription management, merchant-named notifications, spending insights with an annual recap, and per-transaction carbon tracking. Each one fails in a specific way when the transaction record underneath it is not accurate. This piece walks through those failure modes and the exact data fields that prevent them - and shows why a bank scoping these as five separate builds is really buying the same merchant-identity layer five times over.
Industry insights
Chargeback Prevention for Banks: Where Disputes Begin
Chargebacks are an important tool providing clients with the ability to dispute transactions and reclaim funds. These happen when a client contacts their bank to reverse a transaction, often because they believe the transaction was unauthorized, fraudulent, or incorrect. Chargebacks themselves also present significant challenges for merchants, banks, and fintech companies, often resulting in substantial financial losses. And the rise of digital banking has only magnified the importance of efficient chargeback management. With many automation tools available, banks need to understand that prevention is often the cheapest and smartest option available, making clear payment history more important than ever.
Industry insights
How to Build a Digital Bank
Digital banks serve over 500 million customers worldwide, yet fewer than a quarter turn a profit. This guide covers what it takes to build one - licences, architecture, acquisition cost, and the monetisation levers that lead to sustainable margins - with launch stories from Partners Banka and SwissBorg.
Industry insights
How to choose the best open banking data provider for assessing creditworthiness
CCD2 takes effect on 20 November 2026, and self-declared income won't cut it anymore. But open banking data is far messier than a bank's internal records, so the provider you pick decides how reliable your creditworthiness assessment really is. Here's how to run a proof of concept on your own customers and judge vendors on coverage, accuracy, and classification depth.
Industry insights
CCD2: Which EU Countries Are Most Prepared for the New Consumer Credit Directive
CCD2 was meant to be transposed across the EU by November 2025, yet many member states still don't have final legislation. The frontrunners are the Nordics and the Netherlands - and each is rewriting creditworthiness assessment its own way. Here's how the Netherlands, Denmark, Sweden and Finland are tightening the rules, and why no credit register alone is enough to comply.