Tapix
Payment Industry Blog
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Industry insights
Top 135+ Fintech Conferences of 2027: Must-Attend Events for Industry Insights
Fintech and digital banking event lists exist, but they are often fragmented, incomplete, or hard to compare. Relevant conferences are spread across multiple sources with little structure. This curated overview brings them together in one place for 2027.

Product insights
Visa Mandate 2027: What Issuers Must Do
Visa has announced a series of mandates updating how banks and fintechs manage transaction data, cardholder controls, and recurring payments. The changes follow similar regulatory steps taken by Mastercard and aim to improve transparency, consumer trust, and digital control in the European payment ecosystem.

Product insights
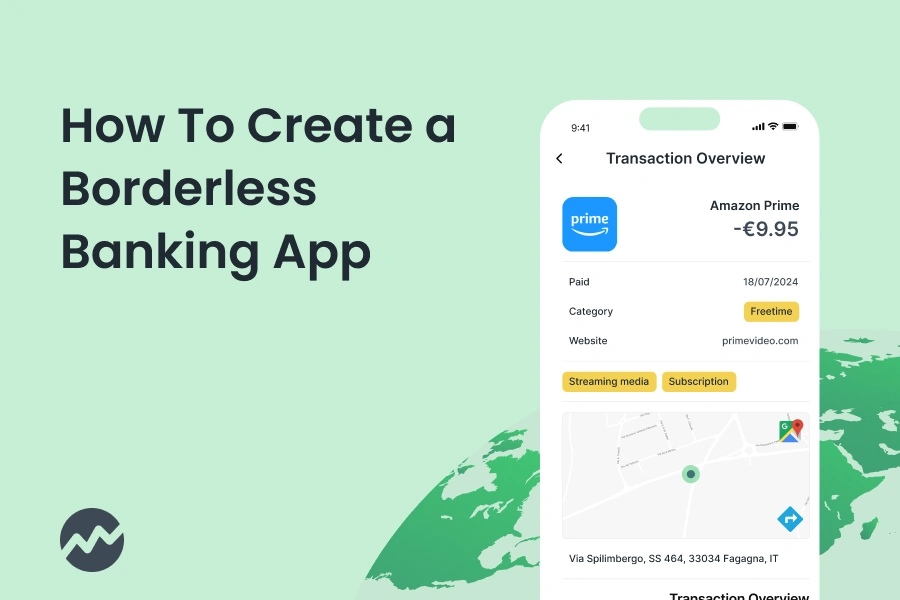
What a Borderless Banking App Needs From Payment Data
A banking app that works perfectly at home can fall apart on the first foreign payment. The domestic feed works because the same merchants repeat week after week - the supermarket, the transport operator, the coffee place near the office. The moment a customer lands abroad and taps their card, that repetition disappears, and the app has to answer a harder question from a single transaction record. This is a build guide for tier 1 banks: which fields a transaction record has to carry abroad, and what a borderless banking app can show once it carries them.
Industry insights
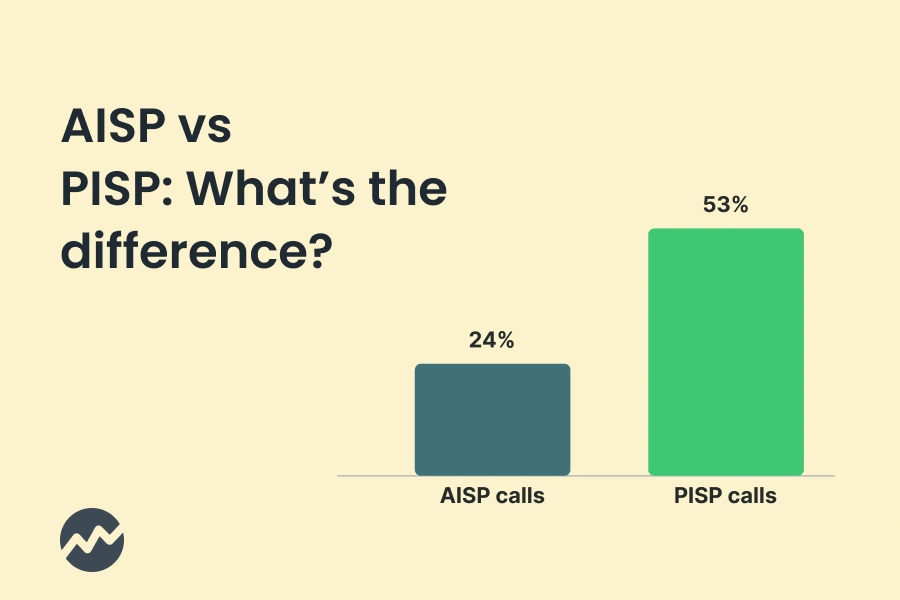
AISP vs PISP: reading payment data vs acting on it
Affordability comes down to one number a lender must evidence: what's left after every expense is paid. That's an account information job start to finish - and it's where the two open banking roles split. An AISP reads the transaction picture that makes affordability calculable; a PISP moves the money once the decision is made, but plays no part in working out whether someone can afford anything. Here's why the two belong in separate boxes, and why adoption is now tilting from the reading role toward the acting one.
Industry insights
The Digital Banking Engagement Playbook: What Actually Pays Back
An established bank earns several times more per customer than a neobank, and almost none of it comes from the app. The money sits on the balance sheet: the salary paid in, the direct debits cleared against it, the loan on the other side of the ledger. But the app is where that relationship gets defended or quietly lost, feature by feature, as customers decide where their financial routine will live. This playbook cuts through engagement vanity metrics to the features that actually move the number that pays back - and shows why every one of them depends on a bank being able to read what its customers' payments really are.
Industry insights
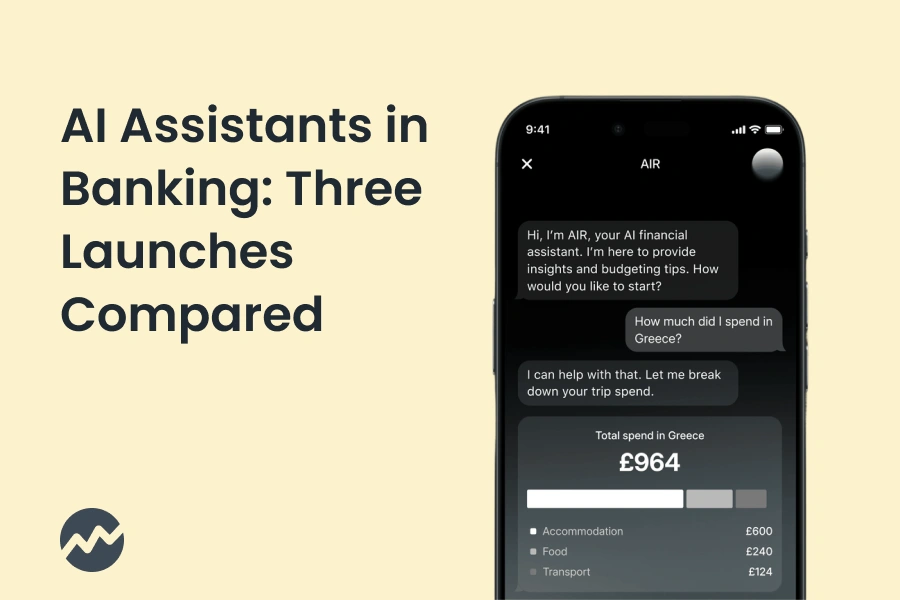
AI Assistants in Banking: bunq, Starling and Revolut
Three banks shipped consumer-facing AI assistants inside twelve months, and to anyone being asked whether their own bank needs one, they look like a single trend. They are not. Measured on what the assistant is allowed to do, what it is allowed to see, and the route each bank took to ship it, bunq Finn, Starling Assistant and Revolut AIR turn out to be three different products - and the differences change what can go wrong with each. Here they are set side by side.
Industry insights
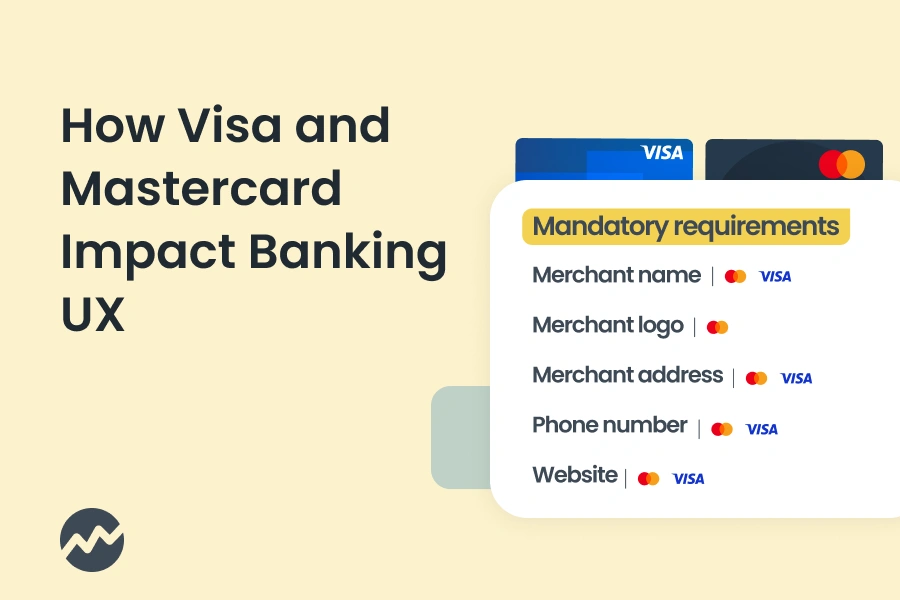
Visa and Mastercard Transaction Data Requirements: How They Shape Banking UX
Visa and Mastercard transaction data requirements are turning transaction clarity from a product decision into an issuer obligation. Some banks used to invest in recognisable merchant names and clean feeds. Others shipped raw descriptions and MCC codes. Now the minimum bar is rising for everyone, and banking UX is where the difference shows.
Industry insights
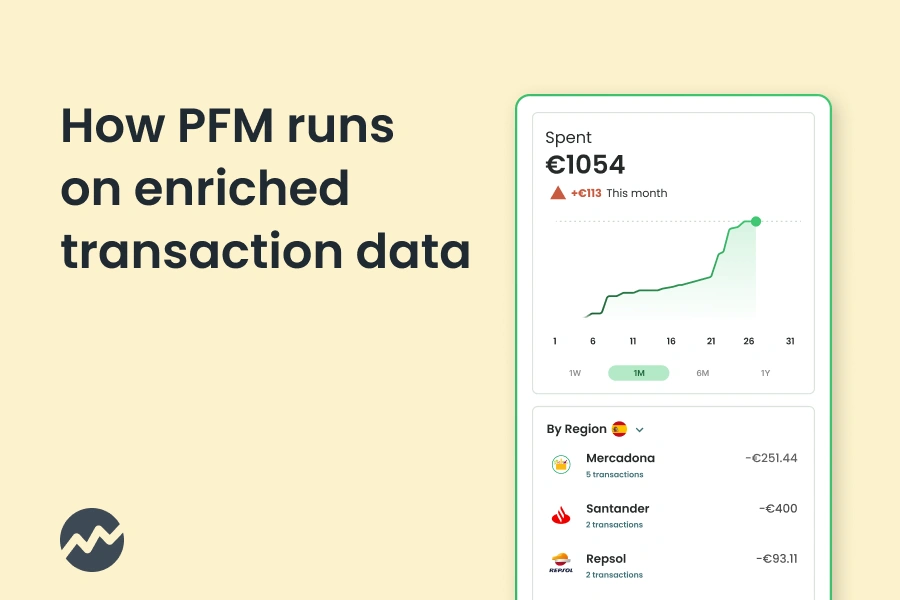
How enrichment expands personal finance management
Every feature in a personal finance app - categories, spending summaries, subscription alerts, carbon insights, even an agent that cancels a forgotten trial - sits on one thing: the quality of the transaction data underneath. Here's how enrichment turns raw payment strings into a PFM customers actually trust, across every payment rail and every market.

Product insights
Subscription management solutions: 4 options for banks explained
"Subscription management" means four different things to four different banks - a simple list, a forecasting overview, a control button, or a security audit. Each serves a distinct motivation and draws on a distinct data source. This article breaks down all four solutions, what each is worth to the customer, and how to weigh them before committing engineering effort.

Industry insights
What does Generation Z expect from banking?
Gen Z is the heaviest-subscribing generation and fails on those subscriptions at roughly twice the rate of everyone else. But subscriptions are only the start. This piece breaks down four things Gen Z actually expects from a bank - seeing what they pay for, getting answers without digging, having their spending reflected back accurately, and banking with an institution that looks like them - and shows the European evidence behind each. Underneath all four sits the same dependency: a clean, enriched transaction record.
Product insights
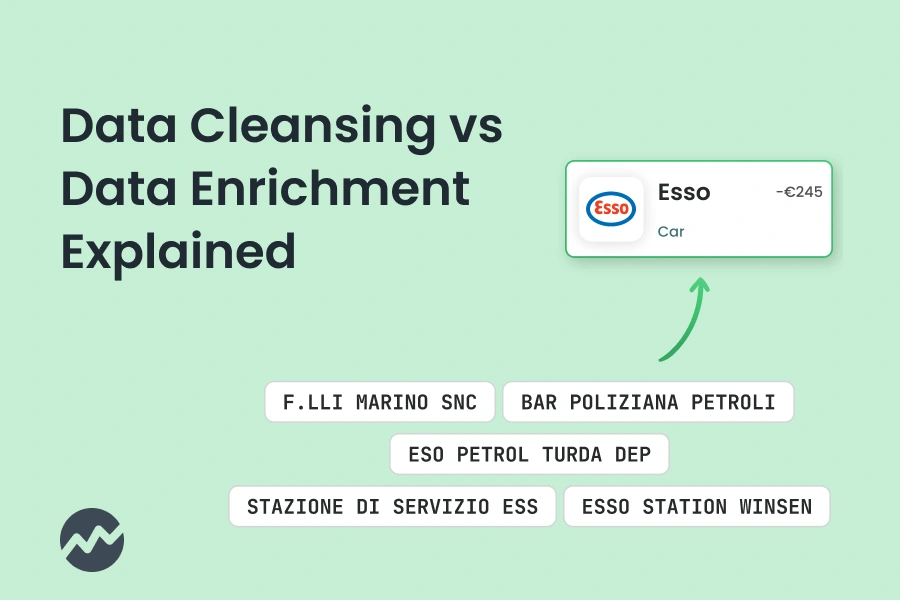
Data cleansing vs Data enrichment: Why your bank needs both
You want to build a subscription manager, a spending overview, or an affordability model - and the transaction feed hands you a terminal string that reads like a licence plate. Getting from that raw string to a shop a customer recognises takes two separate operations: cleansing and enrichment. Here's what each one does, which one your feature actually depends on, and how it holds up across card, SEPA and open banking data.

Industry insights
Top 5 Digital Banking Features for Generation Z
Gen Z decides fast whether a banking app is worth keeping open, and the choice comes down to five features: clear transaction history, subscription management, merchant-named notifications, spending insights with an annual recap, and per-transaction carbon tracking. Each one fails in a specific way when the transaction record underneath it is not accurate. This piece walks through those failure modes and the exact data fields that prevent them - and shows why a bank scoping these as five separate builds is really buying the same merchant-identity layer five times over.
Industry insights
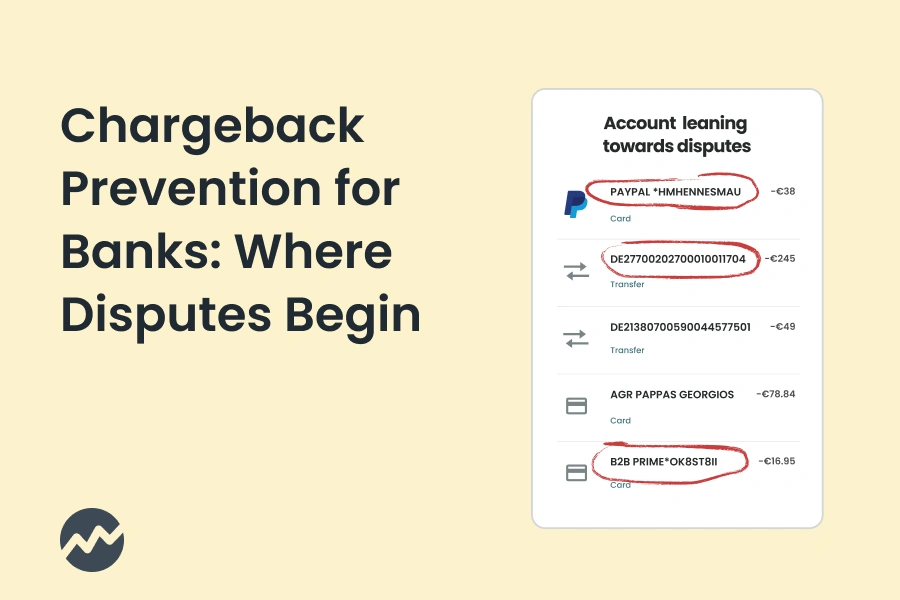
Chargeback Prevention for Banks: Where Disputes Begin
Chargebacks are an important tool providing clients with the ability to dispute transactions and reclaim funds. These happen when a client contacts their bank to reverse a transaction, often because they believe the transaction was unauthorized, fraudulent, or incorrect. Chargebacks themselves also present significant challenges for merchants, banks, and fintech companies, often resulting in substantial financial losses. And the rise of digital banking has only magnified the importance of efficient chargeback management. With many automation tools available, banks need to understand that prevention is often the cheapest and smartest option available, making clear payment history more important than ever.
Industry insights
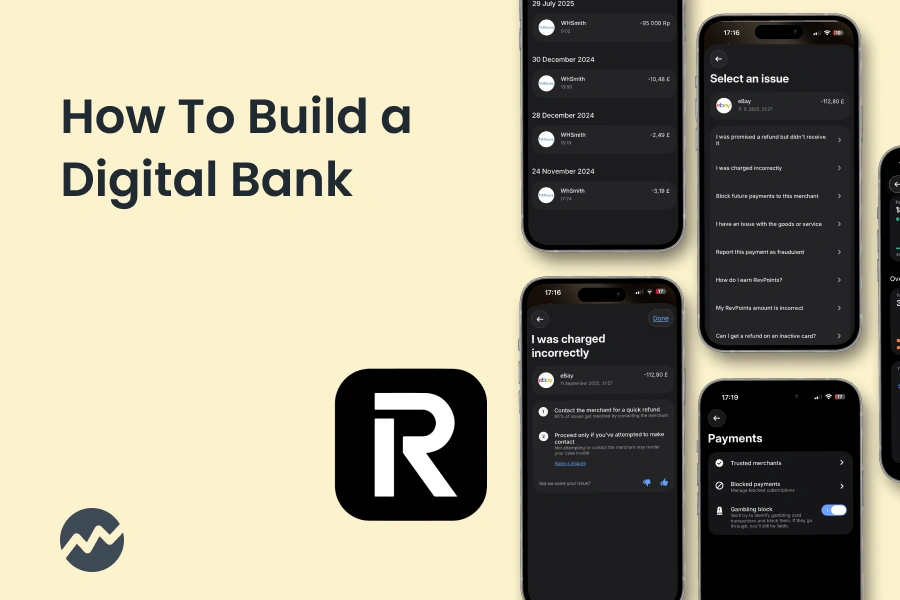
How to Build a Digital Bank
Digital banks serve over 500 million customers worldwide, yet fewer than a quarter turn a profit. This guide covers what it takes to build one - licences, architecture, acquisition cost, and the monetisation levers that lead to sustainable margins - with launch stories from Partners Banka and SwissBorg.
Industry insights
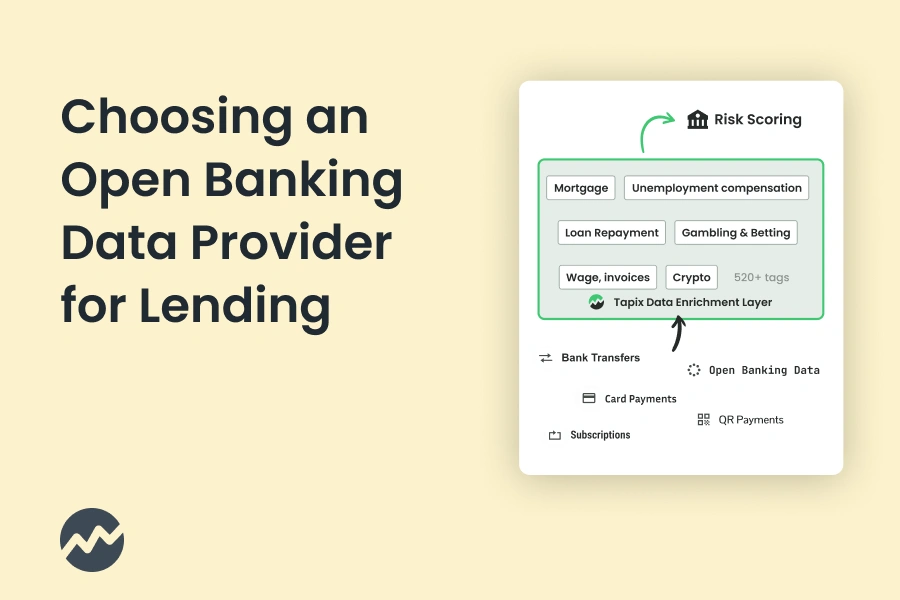
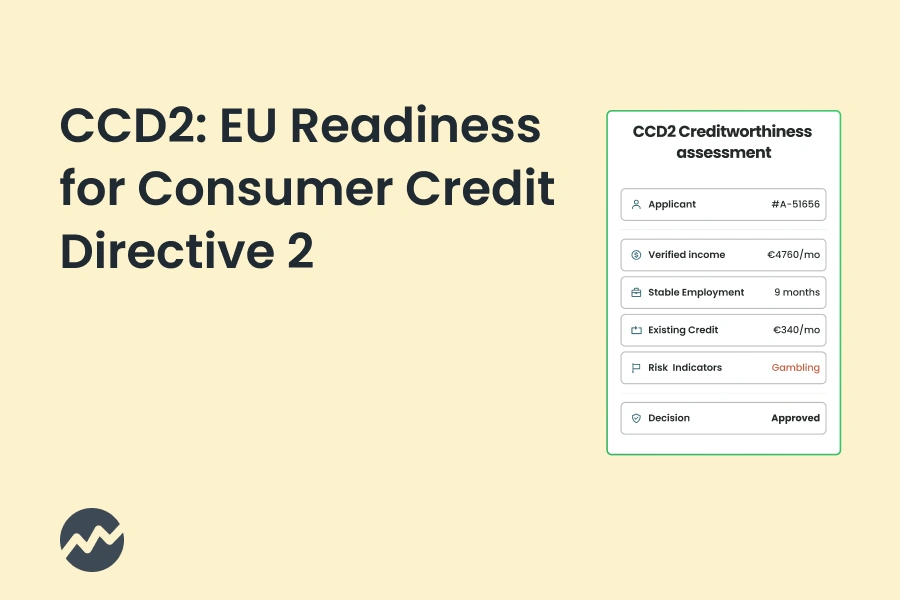
How to choose the best open banking data provider for assessing creditworthiness
CCD2 takes effect on 20 November 2026, and self-declared income won't cut it anymore. But open banking data is far messier than a bank's internal records, so the provider you pick decides how reliable your creditworthiness assessment really is. Here's how to run a proof of concept on your own customers and judge vendors on coverage, accuracy, and classification depth.
Industry insights
CCD2: Which EU Countries Are Most Prepared for the New Consumer Credit Directive
CCD2 was meant to be transposed across the EU by November 2025, yet many member states still don't have final legislation. The frontrunners are the Nordics and the Netherlands - and each is rewriting creditworthiness assessment its own way. Here's how the Netherlands, Denmark, Sweden and Finland are tightening the rules, and why no credit register alone is enough to comply.
Industry insights
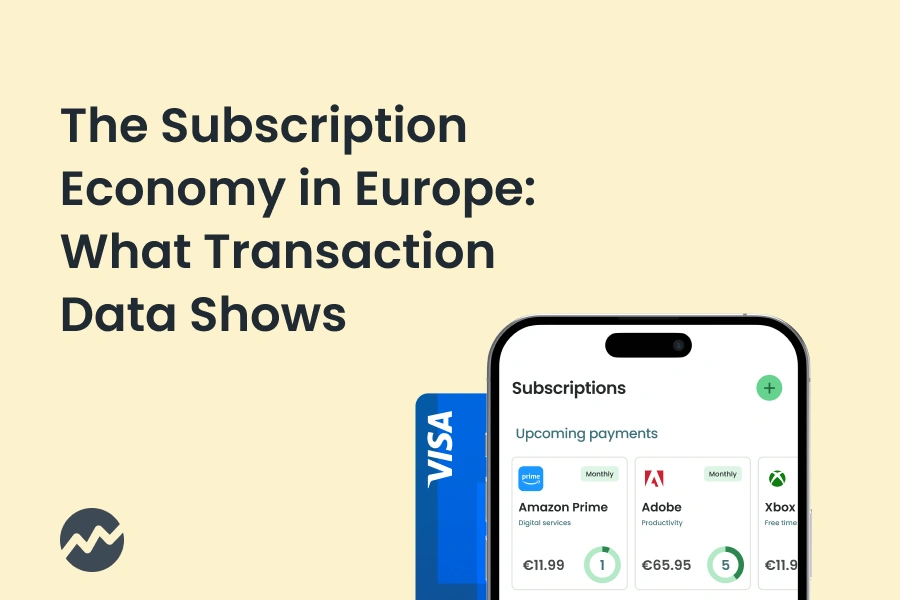
The European Subscription Economy Runs Through Transaction Data. Most Banks Can't Read It
Across Europe, many merchants sell distinct and varied subscription products. That is how the subscription economy appears in bank transaction data: dense, fragmented, and structurally difficult to read. The brand-name surface looks tidy, with Netflix, Spotify and Apple at the front. Underneath, every merchant runs roughly six pricing variations, on average, across different amounts, billing cycles, currencies and payment paths.
Product insights
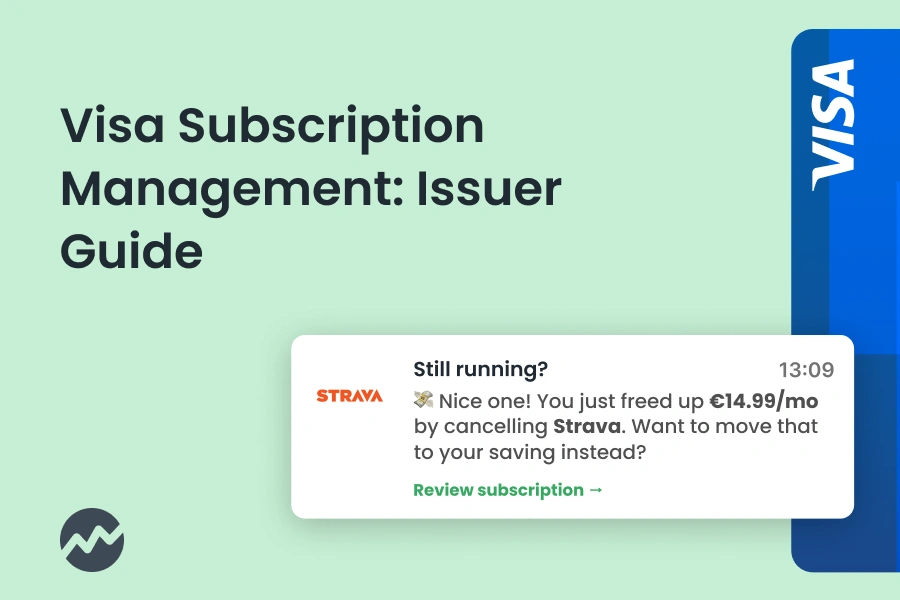
Visa Subscription Management Mandate: A Complete Implementation Guide for European Issuers
Visa subscription management mandate has been in force since 18 April 2026 across 13 European markets, and the question for product teams has moved from whether to build subscription management to how to build it correctly. The full mandate overview covers all three of Visa's 2026/2027 requirements; this article focuses only on and what it takes at the implementation level. The rule asks issuers to do three things: identify and label three recurring transaction types, enable merchant-level stop instructions with the correct decline responses, and inform cardholders that cancelling a card charge does not end their contract with the merchant. None of these are unreasonable. Each one, though, depends on the quality of the transaction data sitting underneath the interface.
